News
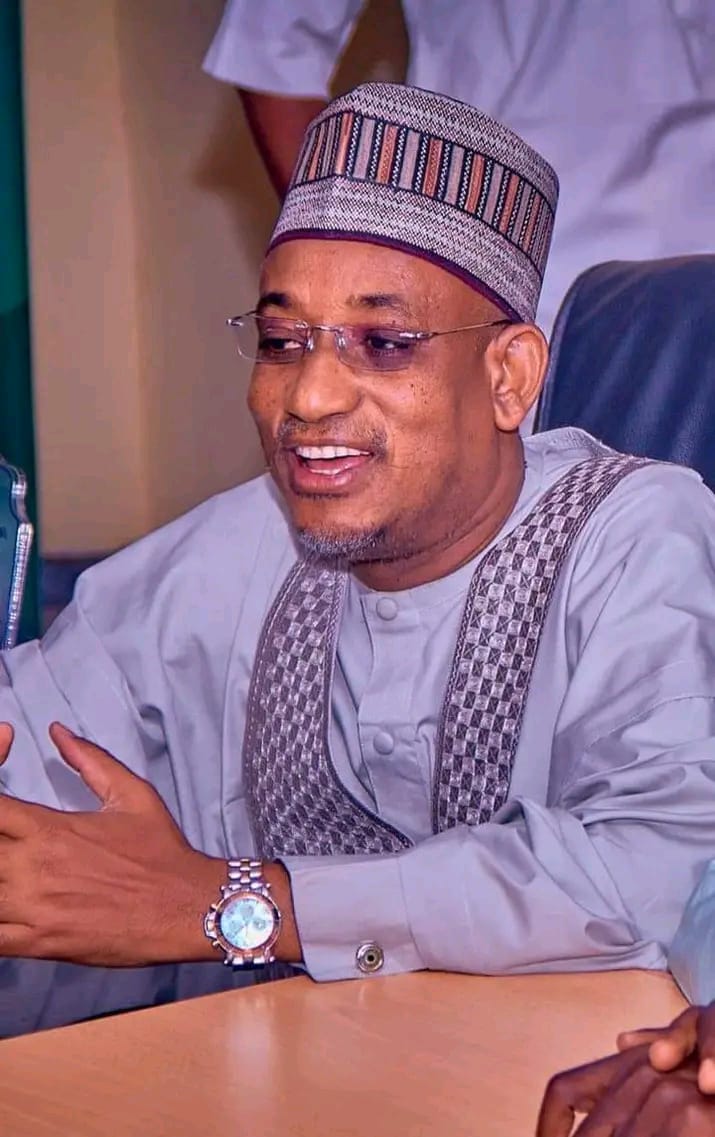
Yobe Speaker commends Governor Buni

Yobe Speaker commends Governor Buni
By: Yahaya Wakili
The Speaker Yobe State House of Assembly, Rt. Hon. Chiroma Buba Mashio, has commended His Excellency, the Executive Governor of Yobe State, Hon. Mai Mala Buni CON Chiroman Gujba, for maintaining the cordial relationship with the legislature for the development of the state.
He made the call while declaring the opening of a Public Accounts Committee (PAC) session on the 2023 State and Local Government Audit report at the conference hall of the Assembly, Damaturu.
Hon. Mashio called on the local government, ministries, departments, and agencies that were queried in the 2023 audit report to cooperate with the house committee on public accounts to depend on their portions.
He revealed that the public accounts committee session, which is a constitutional mandate, will assist government agencies to resolve the public financial level in terms of documentation and recording of financial transactions in the state.
In his welcome address, the Chairman House Committee on Public Accounts, Hon. Bulama Bukar, maintained that as a result of organizing the previous Public Account Committee (PAC) session. Yobe State has achieved a greater position at both the national and international level in terms of documentation and recording of financial transactions in the state.
Hon. Bukar commends the effort of the state and local government auditor general for the timely presentation of the annual audit report to the state house of assembly.
Yobe Speaker commends Governor Buni

Nigeria, Japan Move to Set Up Industrial Hub to Unlock Investment
…Abuja seeks Japanese capital, technology transfer as Tokyo promises faster visa processing
By: Michael Mike
Nigeria is seeking to establish a joint industrial and investment hub with Japan to attract foreign capital, accelerate technology transfer and position local businesses to tap into Japanese supply chains and the wider African market.
The proposal, put forward by the Minister of Foreign Affairs, Ambassador Bianca Odumegwu-Ojukwu, signals Nigeria’s push to turn 66 years of diplomatic relations with Japan into a stronger economic partnership driven by investment, industrialisation and job creation.
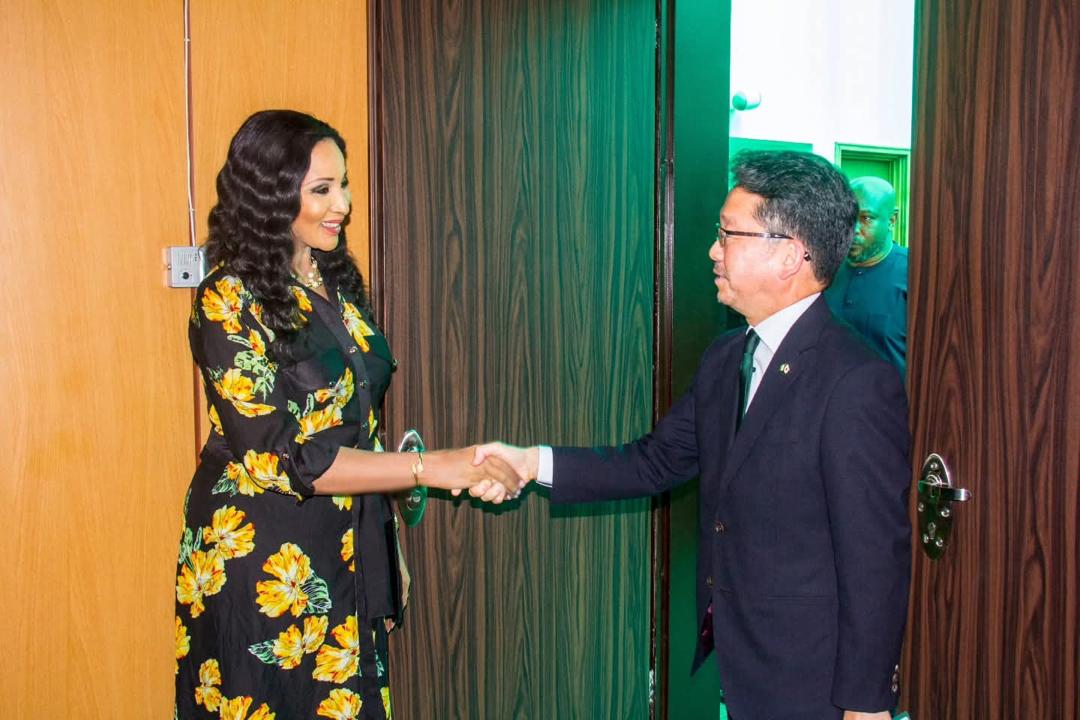
Odumegwu-Ojukwu made the proposal during a bilateral meeting with Japan’s Ambassador to Nigeria, Suzuki Hideo, urging Tokyo to work with Nigeria on a practical roadmap for the proposed Nigeria–Japan Industrial and Investment Hub.
The initiative is expected to facilitate joint ventures, connect investors with credible Nigerian businesses, promote skills development and encourage Japanese companies to establish stronger industrial links with Africa’s largest economy.
The minister stressed that existing bilateral agreements must translate into concrete investment commitments and measurable development outcomes, rather than remain diplomatic declarations.
“The outcomes of the Forum must be translated into concrete programmes, investment commitments and measurable development outcomes,” she said.
She urged both countries to implement the agreements reached at the 10th Nigeria–Japan Special Partnership Forum, held in Abuja on August 27, through practical programmes and regular consultations between their foreign ministries.
To strengthen private-sector participation, Odumegwu-Ojukwu called for more partnerships between Nigerian and Japanese companies through joint ventures, local content development, skills transfer and the integration of Nigerian businesses into Japanese supply chains.
She also sought greater engagement by the Japan External Trade Organization (JETRO) to link Japanese investors with Nigerian enterprises and public-sector partners.
Beyond manufacturing and trade, Nigeria is seeking Japanese investment in solid minerals, gas development, cleaner energy technologies and industrial decarbonisation, with the minister highlighting the strategic importance of resilient energy and critical-mineral supply chains.
The proposed investment push comes alongside Japan’s development cooperation in infrastructure, healthcare, agriculture, education and technical training through the Japan International Cooperation Agency (JICA).
Odumegwu-Ojukwu welcomed a $10 million JICA-supported initiative to strengthen Nigeria’s startup ecosystem through catalytic capital and institutional development, in partnership with the Nigeria Sovereign Investment Authority.
She also called for sustained Japanese support for peacebuilding, humanitarian assistance and stabilisation in Nigeria and West Africa, reaffirming Nigeria’s commitment to regional stability through the African Union and the Economic Community of West African States.
On mobility and business exchanges, the minister urged continued dialogue to resolve visa-related challenges affecting businesspeople, students, researchers, government officials and tourists.
Responding, Suzuki said Japan was desirous of deepening cooperation with Nigeria, which he described as a strategic African giant.
He also assured that visa-related issues would be handled expeditiously, an undertaking that could help facilitate business and people-to-people exchanges between the two countries.
Odumegwu-Ojukwu said the existing cordial relations between Nigeria and Japan offered an opportunity to build a more dynamic partnership anchored on investment, industrialisation, technology transfer and shared prosperity.
The renewed engagement comes as both countries seek to move beyond decades of diplomatic relations towards stronger commercial ties, with the proposed industrial hub emerging as a potential platform for converting bilateral goodwill into investments and economic opportunities.
Nigeria, Japan Move to Set Up Industrial Hub to Unlock Investment
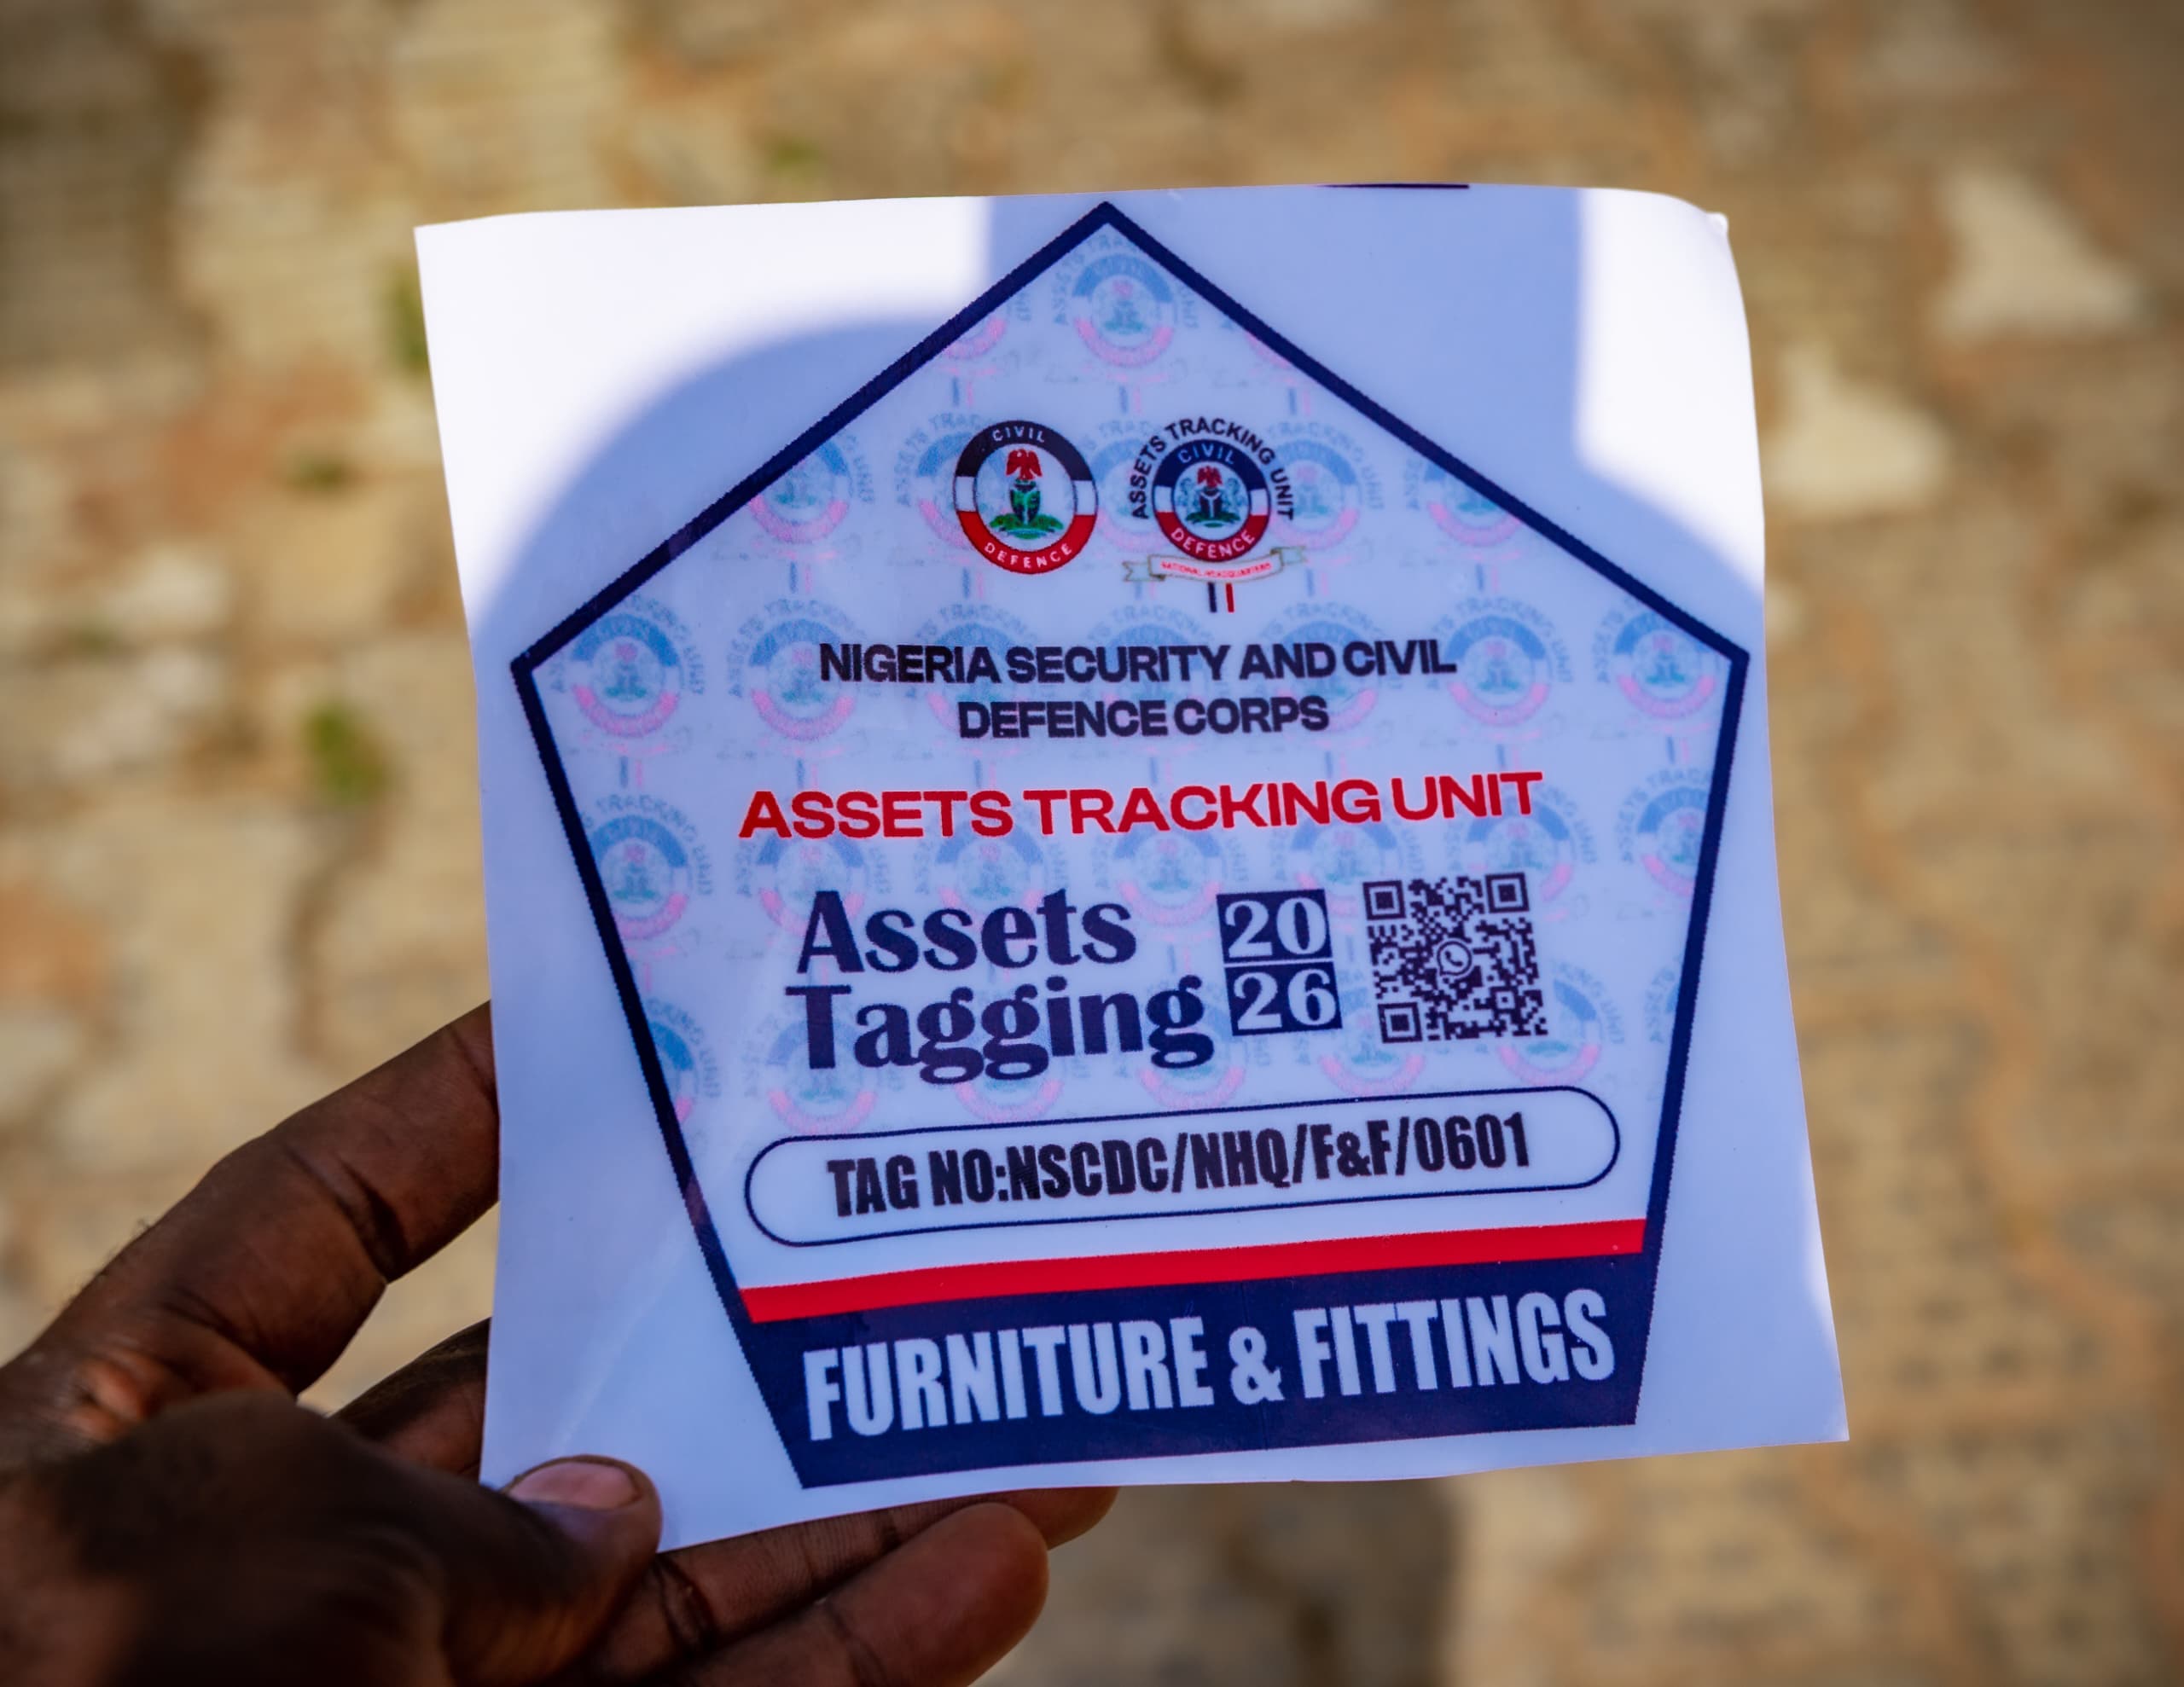
NSCDC Begins Asset Tagging to Curb Mismanagement of Public Property
By: Michael Mike
The Nigeria Security and Civil Defence Corps (NSCDC) has launched an asset coding and tagging exercise aimed at strengthening accountability, tracking institutional property and preventing the misuse of public resources.
The Commandant-General of the Corps, Prof. Ahmed Audi, said the initiative would improve transparency, operational efficiency and the utilisation of government assets across the organisation.
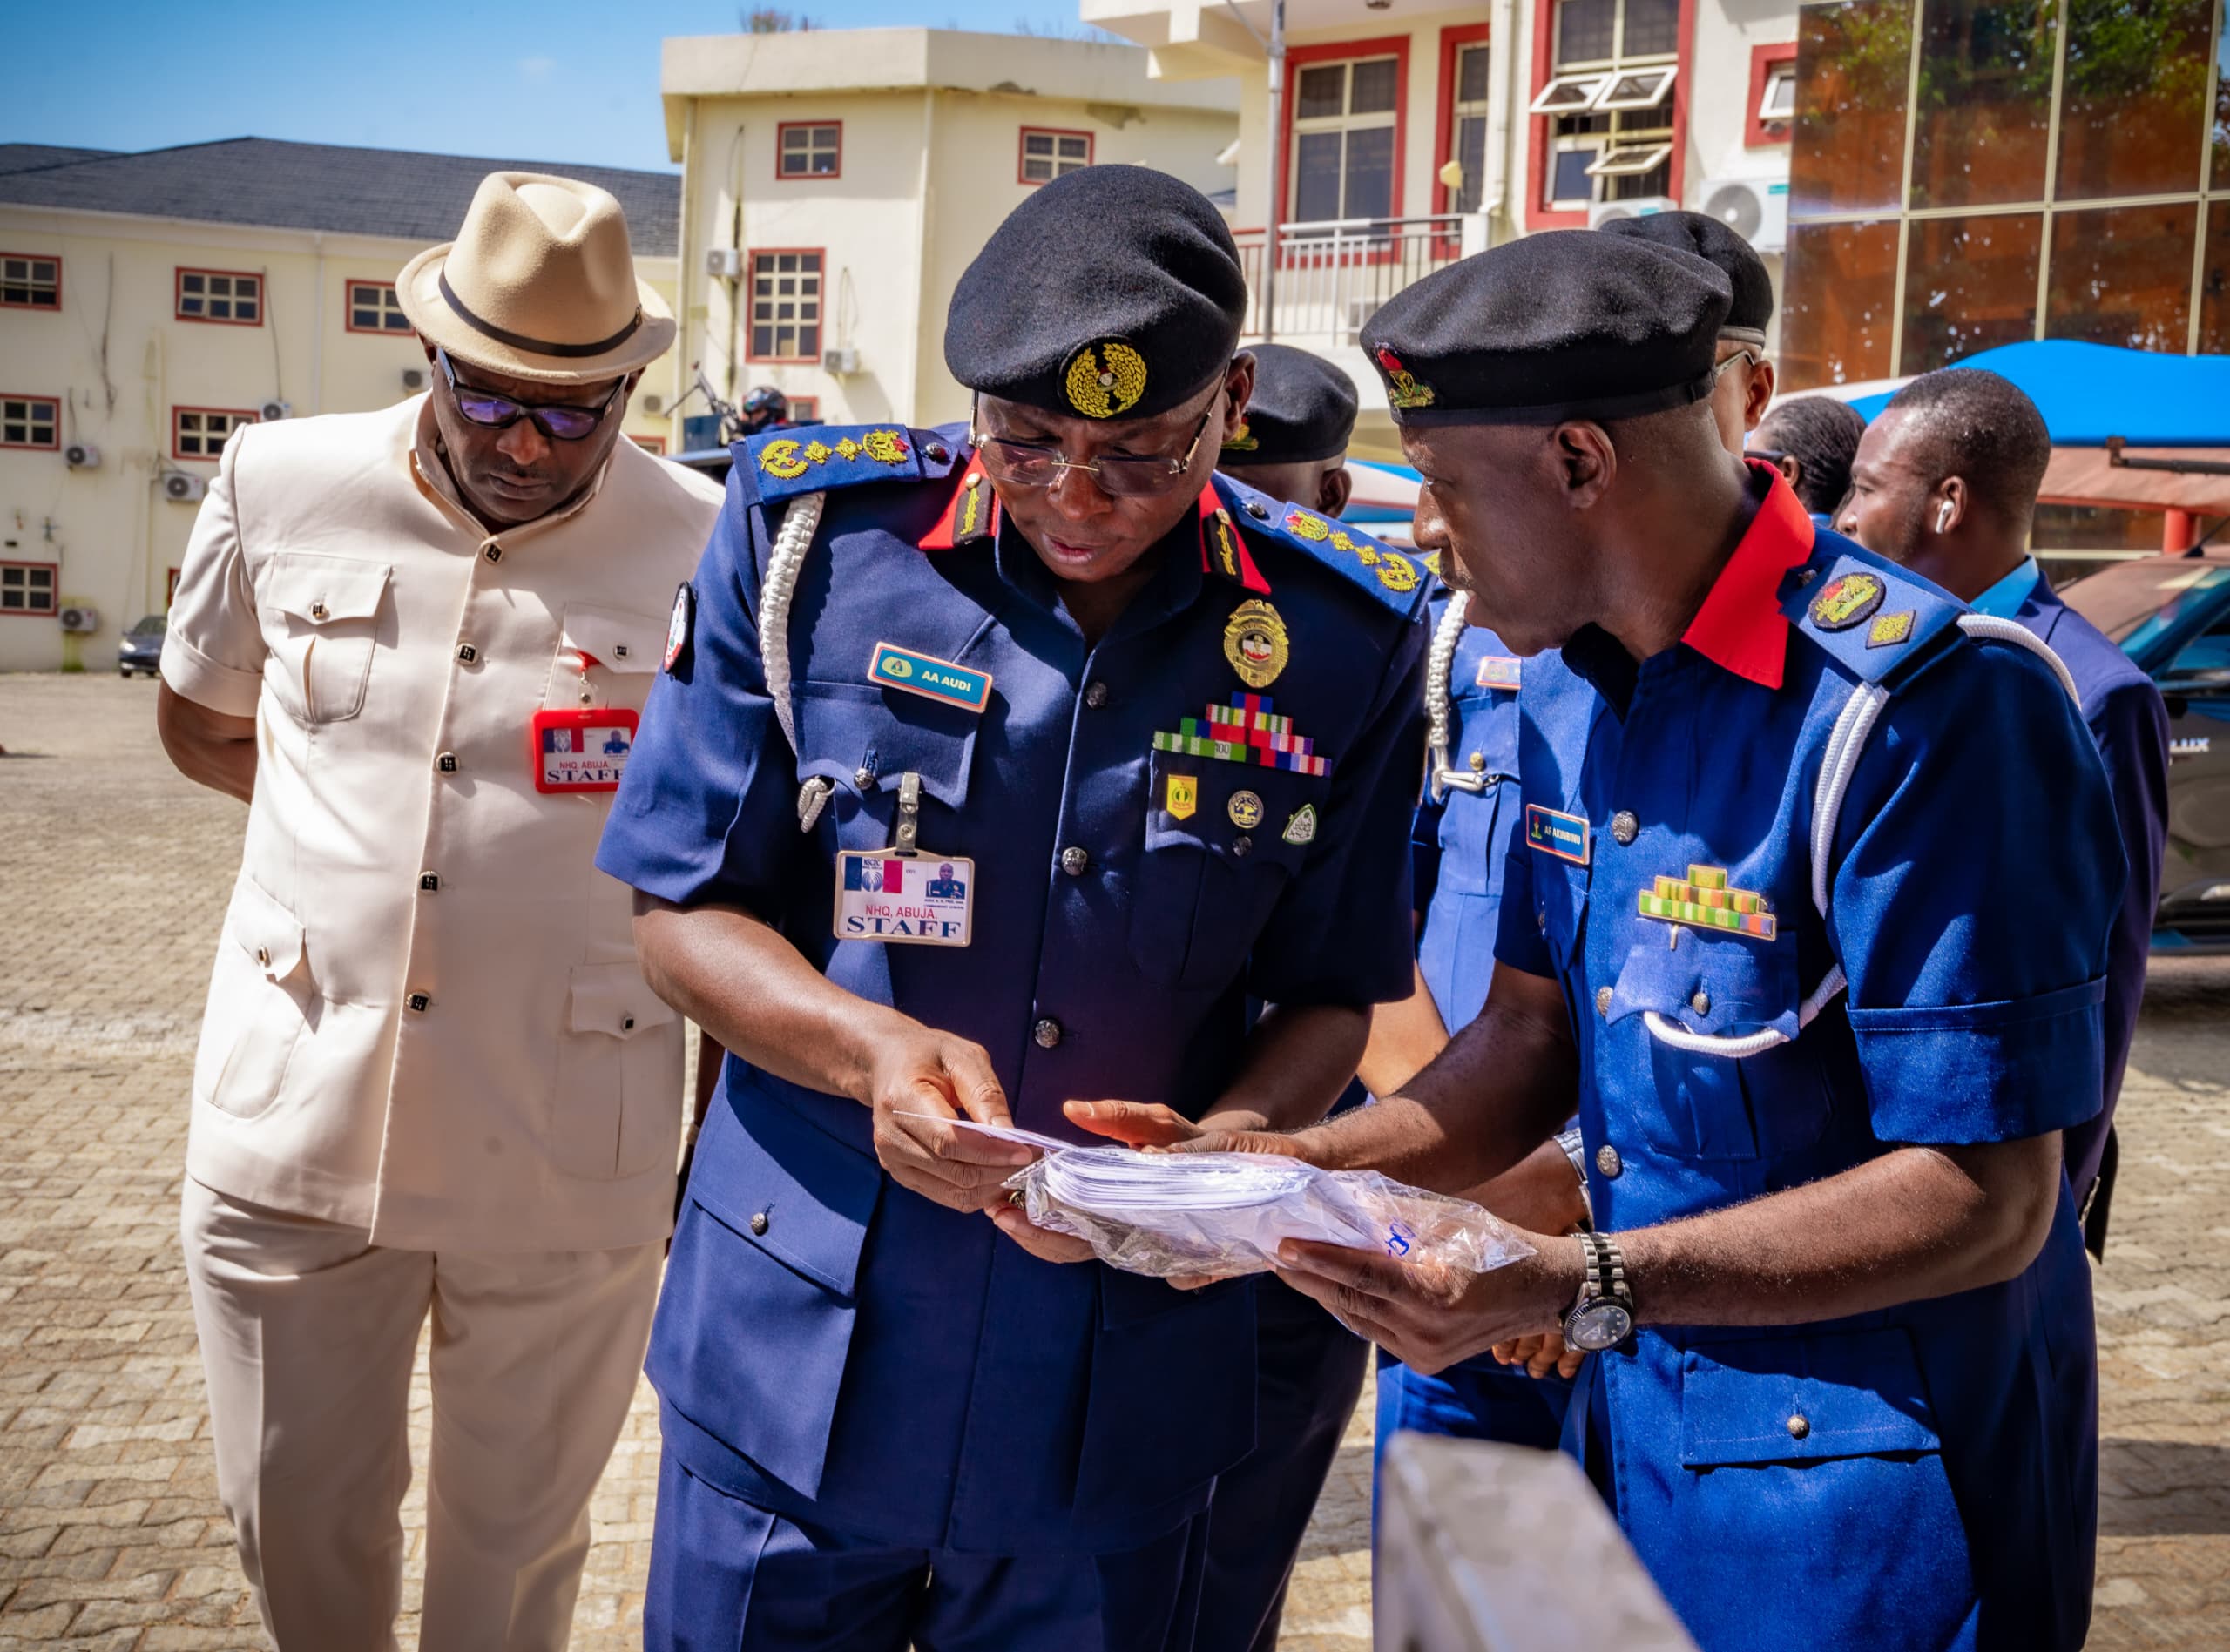
Audi gave the charge on Tuesday during the official flag-off of the exercise at the NSCDC National Headquarters in Abuja, urging personnel to demonstrate discipline and accountability in the management of institutional property.
He stressed that the assets were public property entrusted to the Corps and must be protected against misuse, neglect and mismanagement.
The Commandant-General also called on top management officers to cooperate fully with the exercise, which is expected to strengthen asset tracking and improve records of the Corps’ property.
Earlier, the Head of the Tracking Assets Unit, CSC Akinbinu Festus, described the exercise as a demonstration of the Corps’ renewed commitment to accountability and responsible asset management.
In his vote of thanks, ACG Faruk Musa Boyi commended Audi for initiating the exercise, stressing the importance of maintaining accurate asset records.
The event was attended by Deputy Commandants-General and other senior management officers, reflecting the Corps’ commitment to strengthening institutional accountability and improving resource management.
NSCDC Begins Asset Tagging to Curb Mismanagement of Public Property
MIKTA Nations Push Climate Finance Reforms as Nigeria Faces $337bn Funding Gap
By: Michael Mike
Nigeria will require an estimated $337 billion between 2026 and 2035 to implement its climate commitments, highlighting the enormous financing challenge confronting the country as international partners intensify calls for a more accessible and effective global climate finance system.
The funding requirement came into focus at a climate finance engagement in Abuja, where representatives of five countries under the MIKTA partnership—Mexico, Indonesia, South Korea, Türkiye and Australia—joined Nigeria’s National Council on Climate Change (NCCC) in advocating practical solutions to the gap between climate ambitions and the resources available to implement them.
The discussions centred on improving access to climate finance, mobilising private investment, expanding technology transfer, strengthening sustainable finance mechanisms and ensuring that international commitments translate into projects capable of delivering measurable results.
With countries preparing for the 31st United Nations Climate Change Conference, COP31, the speakers argued that the effectiveness of global climate action would depend not only on the amount of money pledged but also on whether vulnerable countries could access the funds without excessive bureaucratic, financial and institutional barriers.
Nigeria’s position was presented by Jummai Vandu, who represented the Director-General of the NCCC, Tenioye Majekodunmi. She highlighted the country’s substantial financing needs under its Nationally Determined Contribution 3.0 (NDC 3.0), which sets out its climate commitments for the coming years.
The $337 billion requirement underscores the scale of investment needed to advance mitigation and adaptation, strengthen resilience and support Nigeria’s transition towards a lower-carbon economy.
For Nigeria, the challenge extends beyond securing commitments from international partners to developing investment-ready projects, improving coordination among institutions and ensuring that available resources reach the sectors and communities that need them most.
The discussions also pointed to the importance of aligning climate action with national development priorities, including energy access, economic diversification, job creation and social inclusion.
Türkiye’s Ambassador to Nigeria, Mehmet Poroy, emphasised the need to close the gap between climate commitments and projects capable of attracting financing.
His intervention focused on the proposed Climate Implementation Bridge, an approach intended to help countries translate their climate plans into bankable projects and connect those projects with potential sources of funding.
The proposal reflects a persistent challenge in developing countries, where ambitious climate strategies often struggle to progress because of inadequate project preparation, limited technical capacity and difficulties attracting private capital.
The approach places emphasis on moving beyond declarations of intent towards practical implementation in areas such as renewable energy, climate-resilient agriculture, green industrialisation, food security and the circular economy.
For Nigeria and other developing economies, this would require stronger collaboration between governments, development institutions, investors and technical partners to identify viable projects, prepare them to meet financing requirements and improve the prospects of implementation.
Poroy’s intervention reinforced the broader message of the meeting: climate finance must be connected to a credible pipeline of projects if it is to produce tangible economic and environmental benefits.
Australia’s High Commissioner to Nigeria, Leilani Bin-Juda, called for reforms to make climate finance more accessible, particularly for developing countries and communities most exposed to the effects of climate change.
She highlighted an action plan on access to climate finance for small island developing states and least developed countries, a Pacific-led initiative developed through consultations involving vulnerable countries, development banks and multilateral climate funds.
The plan, launched at a pre-COP meeting in Fiji on October 8, seeks to address barriers that prevent countries from obtaining climate funding, including complicated applications, fragmented financing arrangements, demanding reporting requirements and lengthy approval processes.
Debt pressures, limited fiscal space and high borrowing costs further complicate access, making it difficult for countries already facing significant climate risks to finance adaptation and resilience measures.
Bin-Juda said the initiative had a global ambition and called for wider support beyond the Pacific, including from Nigeria and other African countries.
She stressed that the priority should be to ensure that climate finance responds more effectively to countries’ needs, with simpler application and disbursement processes, stronger national capacity to develop investment-ready projects and greater mobilisation of private capital alongside public and grant financing.
The plan also provides for annual high-level forums to assess progress and share lessons between 2027 and 2030.
For Australia, success would ultimately be measured by whether vulnerable countries could obtain the resources they need when they need them and convert those resources into stronger, more resilient communities.
Indonesia’s Ambassador to Nigeria, Bambang Suharto, highlighted the importance of sustainable financing mechanisms and international cooperation in supporting climate action.
His intervention drew attention to instruments such as green sukuk, sustainable finance taxonomies and other mechanisms capable of directing investment towards environmentally beneficial projects.
Green sukuk can help mobilise funds for eligible projects while broadening the pool of investors participating in climate-related financing. Sustainable finance taxonomies, meanwhile, provide criteria for identifying economic activities that qualify as environmentally sustainable, helping investors assess projects and allocate capital.
Indonesia’s experience also illustrates the importance of aligning climate finance with national development priorities and long-term emissions goals. The country has set a net-zero emissions target for 2060 or earlier.
The broader challenge, as reflected in the discussions, is to ensure that innovative financial instruments are supported by credible standards, transparent reporting and projects that can demonstrate measurable environmental and economic benefits.
International cooperation and the exchange of experience would be essential in helping developing countries adapt these instruments to their own financial systems and investment needs.
South Korea’s representative, Jeong Yo-an, emphasised the importance of technology, knowledge-sharing and cooperation in translating climate commitments into practical outcomes.
The intervention highlighted the value of partnerships that enable countries to share technical expertise, strengthen institutional capacity and deploy solutions suited to their development circumstances.
Technology transfer is particularly important for countries seeking to expand clean energy, improve industrial efficiency and strengthen resilience without undermining economic growth.
For Nigeria, cooperation in these areas could help address technical and institutional gaps that often prevent climate strategies from progressing from policy documents to implementation.
The discussion also reinforced the need for partnerships that combine financing with technical support, ensuring that countries have both the resources and the capacity to execute climate projects effectively.
Mexico’s Chargé d’Affaires, José Manuel Briseño Flores, highlighted the role of sustainable finance frameworks in directing investment towards climate action and other development priorities.
His intervention focused on mechanisms including sustainable finance taxonomies and green, social and sustainability bonds, which can help channel capital into projects with defined environmental or social objectives.
Such instruments can provide governments and businesses with additional avenues for raising funds for renewable energy, climate resilience and other sustainable development initiatives.
However, their effectiveness depends on clear standards, transparency and credible systems for demonstrating how funds are used and what results they achieve.
Developing bankable projects and establishing reliable frameworks for sustainable investment would therefore be crucial to attracting more capital, particularly from private investors.
The Mexican position complemented the wider call for financing systems that do more than announce funding commitments and instead provide a clear pathway from investment decisions to measurable outcomes.
Taken together, the interventions pointed to a common concern: the growing distance between the scale of climate action required and the ability of vulnerable and developing countries to finance it.
The global climate finance debate has increasingly focused on mobilising larger sums, but the Abuja discussions highlighted the equally important questions of accessibility, affordability, project preparation and accountability.
For Nigeria, the $337 billion estimated requirement under NDC 3.0 makes these issues particularly urgent.
Securing financing would need to go hand in hand with stronger institutions, credible project pipelines, improved coordination and investment frameworks capable of attracting both domestic and international capital.
The country would also need to ensure that climate investments support its wider development objectives, including improved energy access, economic opportunities and protection for communities vulnerable to climate impacts.
The MIKTA countries’ interventions offered different approaches to the same challenge: Türkiye’s emphasis on connecting commitments with bankable projects; Australia’s push for simpler access to climate finance; Indonesia’s focus on innovative financial instruments; South Korea’s advocacy of technology and knowledge-sharing; and Mexico’s support for sustainable investment frameworks.
Nigeria’s NCCC, meanwhile, underscored the scale of the domestic financing challenge and the importance of mobilising resources to implement the country’s climate commitments.
As preparations for COP31 gather momentum, the central question remains whether international cooperation can deliver a financing system that developing countries can access in practice, rather than one whose promises remain difficult to convert into action.
For Nigeria, the stakes extend beyond meeting international climate targets. They include the country’s ability to finance a more resilient economy, attract green investment and ensure that climate action delivers practical benefits for its people.
MIKTA Nations Push Climate Finance Reforms as Nigeria Faces $337bn Funding Gap

2027: Tinubu, Shettima, Uba Sani, and the APC flag-off campaign in Kaduna

Nigeria, Japan Move to Set Up Industrial Hub to Unlock Investment

NSCDC Begins Asset Tagging to Curb Mismanagement of Public Property

Roger Federer’s Shock as DNA Results Reveal Myla and Charlene Are Not His Biological Children
THE PLIGHT OF FARIDA

FAILED COUP IN BURKINA FASO: HOW TRAORÉ NARROWLY ESCAPED ASSASSINATION PLOT AMID FOREIGN INTERFERENCE CLAIMS
-
 News3 years ago
Roger Federer’s Shock as DNA Results Reveal Myla and Charlene Are Not His Biological Children
-
Opinions5 years ago
THE PLIGHT OF FARIDA
-
 News2 years ago
FAILED COUP IN BURKINA FASO: HOW TRAORÉ NARROWLY ESCAPED ASSASSINATION PLOT AMID FOREIGN INTERFERENCE CLAIMS
-
 Opinions5 years ago
POLICE CHARGE ROOMS, A MINTING PRESS
-
 News3 years ago
EYN: Rev. Billi, Distortion of History, and The Living Tamarind Tree
-
 ACADEMICS3 years ago
A History of Biu” (2015) and The Lingering Bura-Pabir Question (1)
-
 Columns3 years ago
Army University Biu: There is certain interest, but certainly not from Borno.
-
 Politics1 year ago
2027: Why Hon. Midala Balami Must Go, as Youths in Hawul and Asikira/Uba Federal Constituency Reject ₦500,000 as Sallah Gift
